When pay swings, I split buys into a fast sweep and a slow sweep so I don't overcommit on a temporary high.
The two-sweep buy plan for lumpy paychecks
The moment my income started swinging, my old autopilot broke. When I was salaried and steady, I could set a monthly transfer to my brokerage and forget it. Once bonuses, commissions, or contract checks entered the chat, I noticed a pattern: I would invest aggressively right after a big deposit (because I felt flush), then hesitate the next month (because I felt like I'd already done enough). That whiplash is expensive, mostly because it turns investing into a mood.
What worked for me was splitting every month into two separate moves. Sweep one is the fast sweep: the day a paycheck hits, I send a fixed amount into my core holdings. For me that means broad, boring index funds or ETFs I already own, bought at the same cadence whether I'm up or down. The number is intentionally a little conservative so it still feels doable in the lean months.
Sweep two is the slow sweep: once a month, on a calendar day I choose ahead of time, I look at the cash that piled up from the "extra" months and decide how much of that to deploy. Not all of it. Just a portion. I treat it like seasoning, not the whole meal. If the money came from a one-off project or a single unusually large bonus, the slow sweep is where I protect myself from mistakenly baking that spike into my permanent investing lifestyle.
Mechanically, this is easy in most brokerages: set an automatic buy for sweep one, then keep sweep-two cash in the settlement account or a money market fund until your monthly date. The hard part is psychological. You have to accept that you are allowed to invest more slowly when your income is noisy. When I got that part right, I stopped doing the worst thing, which is making one giant purchase on a high-income month and calling it a plan.
Build a volatility buffer before you chase higher returns
When earnings change fast, the investing mistake I see (and have made) isn't picking the wrong ETF. It's accidentally forcing yourself to sell or pause at the exact wrong time because your cash management couldn't handle a couple of weird months. If your pay can dip, you need a buffer that is designed for dips, not a generic emergency fund you never touch. I keep mine boring on purpose: a high-yield savings account or a money market fund at the brokerage, where the statement is clean and the money is there when I need it.
Here's how I size it in practice. I start with my minimum monthly spend: housing, insurance, utilities, groceries, debt payments, and the truly non-negotiable stuff. Then I add the expenses that tend to show up at the worst times, like quarterly insurance premiums or a property tax bill, because those are the ones that can force you to raid your portfolio if you don't plan. If your income is commission-heavy or project-based, I also include the months where you're working but not getting paid yet. That lag is real, and it doesn't care how bullish you feel.
Once that buffer exists, my investing behavior gets cleaner. I can keep buying through down months because I'm not staring at a checking account that looks like a joke. And when a big check hits, I don't feel pressured to throw all of it into the market immediately just to prove I'm "good with money." I can park it, let it cool off, then deploy it using the same rules I use in normal months.
One small, very specific thing that helped: I keep the buffer in a separate account with a name that matches its job. Not a cute name, just literal. When it was labeled Cash, I treated it like spare change. When it was labeled Income Volatility Buffer, I stopped pretending it was available for random upgrades, and my investing schedule stopped getting interrupted by predictable life bills.
When your income spikes, don't let your asset mix drift
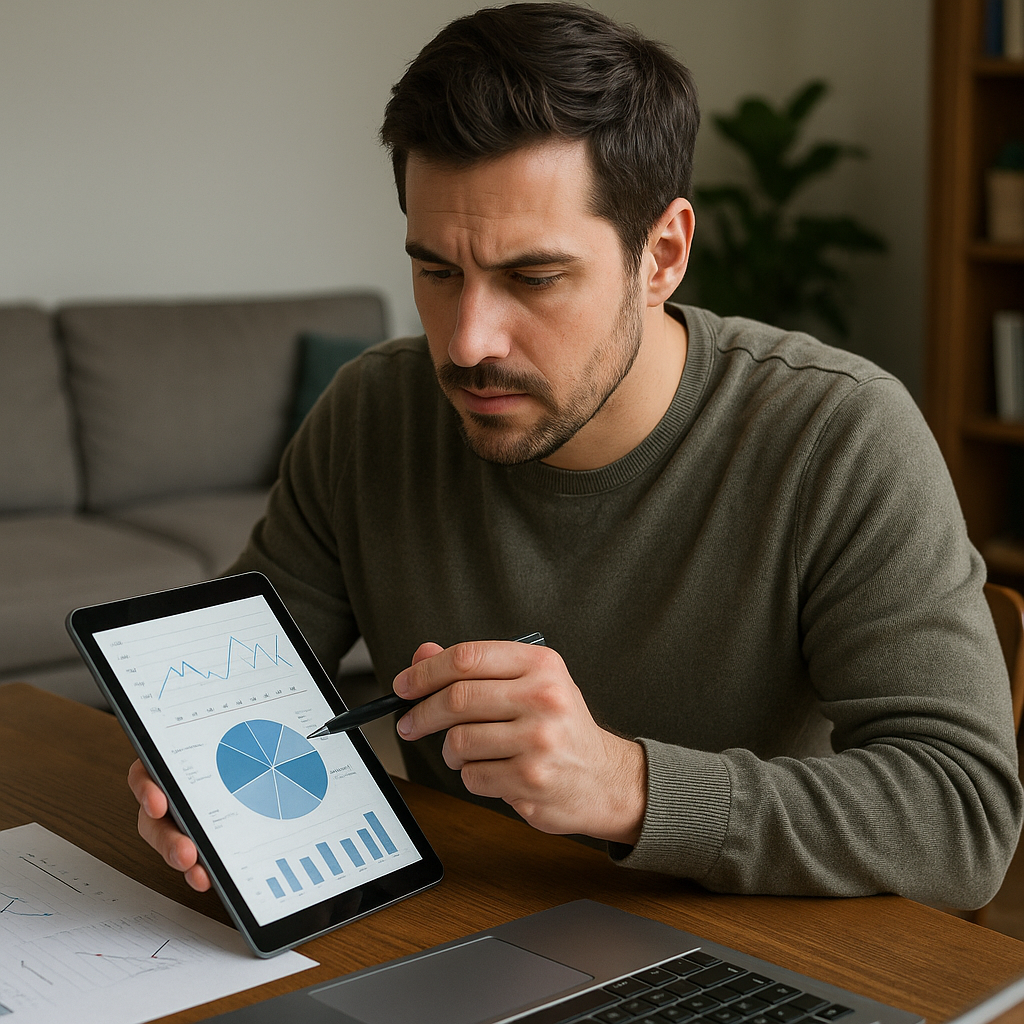
The sneakiest part of fluctuating earnings is how it changes your portfolio without you noticing. Not through some dramatic trade. Through drift. A couple of high months can lead to a burst of stock buys, and then a couple of low months can lead to no buys at all. On paper, nothing looks wrong. In reality, your asset allocation has been tugged around by your income cycle.
I deal with this by making my targets painfully simple and then using contributions to correct drift, not create it. I pick an allocation I can stick with (for example, a broad US stock fund, an international fund, and a bond fund, or a single target-date fund if I want it even simpler). Then I check it on a schedule, not when I feel nervous. If I'm off target, I direct the next buys to the lagging piece. No heroics. No big rebalance trades unless I'm really far off.
Where the income spike matters most is temptation. A sudden run of strong months makes it feel reasonable to lean harder into the riskiest part of your portfolio because you feel like you can afford it now. But if those months are seasonal, or tied to a client that might leave, you've just let a temporary income condition rewrite your long-term risk. I've done that. It felt smart for about six weeks.
A practical trick: decide in advance what a spike means. For me, it does not change my overall mix. It changes the pace at which I fund the mix. If I want to take on more risk, I write down a new target allocation and wait a full quarter before I implement it. That waiting period is not for the market, it's for me. Most of my impulsive "I should be more aggressive" ideas do not survive a normal Tuesday in the following month, and I'm fine with that.